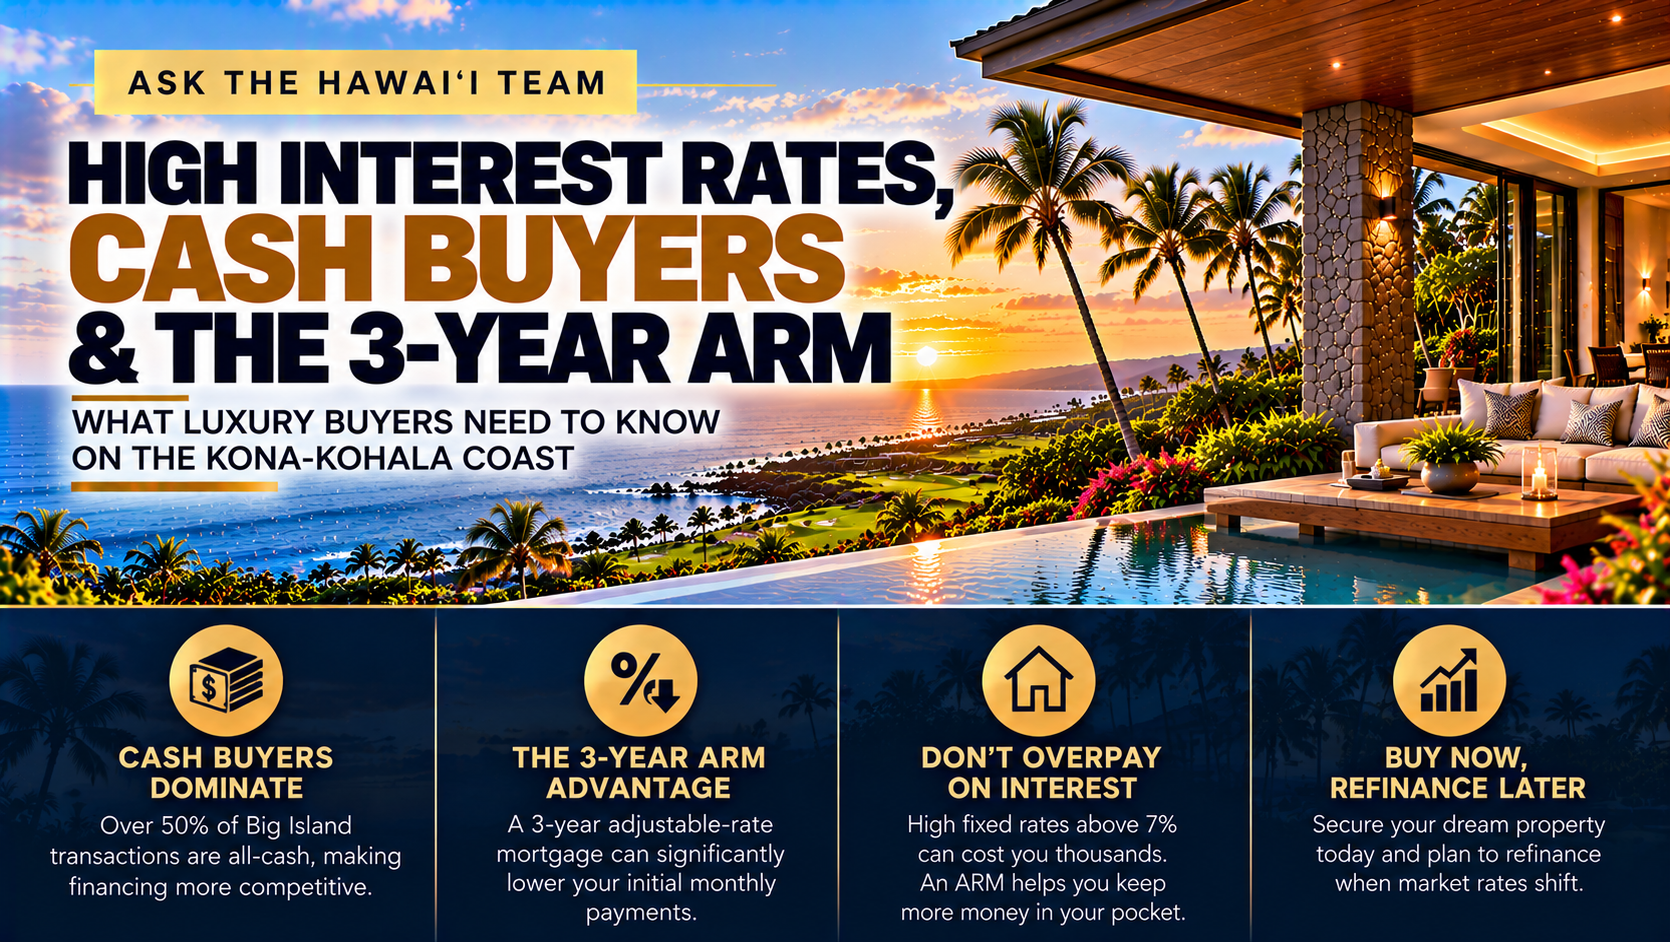
Quick Answer: High interest rates are depressing the traditional financing market while cash buyers dominate over 50% of transactions on the Big Island. However, opting for a 3-year adjustable-rate mortgage (ARM) instead of a fixed loan can save luxury buyers a boatload of cash on high-end properties in resorts like Hualalai and Mauna Kea.
Key Takeaways
- Cash Domination: Over half of Big Island transactions are currently all-cash, leaving financed buyers at a disadvantage unless they optimize their loan structure.
- The ARM Stigma: Many buyers fear ARMs due to historical rate risks, missing out on immediate, substantial monthly savings in today’s high-rate environment.
- Strategic Timeline: A 3-year ARM lowers your initial cost of borrowing significantly when purchasing a luxury second home or vacation rental along the Kohala Coast.
- Refinancing Flexibility: Savvy buyers use short-term ARMs to secure their dream condo or estate now, planning to refinance when market interest rates shift.
Navigating current interest rates on the Kona-Kohala Coast requires moving past outdated financial fears and looking at tactical loan structures. Here is a breakdown of how buyers and sellers are addressing mortgage strategies in today’s luxury market.
Are Adjustable-Rate Mortgages Too Risky for Buying a Second Home on the Kona-Kohala Coast?
More often than not, buyers let historical fear dictate their financial decisions when purchasing a second home or vacation rental. They hear “adjustable-rate mortgage” and automatically assume catastrophic risk, preferring to lock into an expensive 30-year fixed loan sitting above 7%. It is simply economics: locking in a high fixed rate means bleeding thousands of dollars unnecessarily every single month. When you analyze the real data of holding a property for a short-to-medium window, a 3-year ARM removes that immediate monthly burden. I would not be surprised to see more savvy buyers embrace this structure to protect their liquidity. By utilizing my structured approach to financing, you mitigate the perceived dangers of an ARM. Instead of fearing the unknown adjustment period, you treat the short-term mortgage as a tactical tool to acquire prime coastal real estate without overpaying banks for a fixed rate you won’t keep for three decades anyway.
How Much Money Can I Actually Save Using a 3-Year ARM on a Luxury Condo in Waikoloa Beach Resort?
When purchasing a high-end condo in Waikoloa Beach Resort, the difference between a traditional fixed mortgage and a 3-year ARM translates to thousands of dollars in annual savings. With fixed-rate mortgages hovering above 7%, your monthly debt service eats heavily into your vacation rental ROI or second-home enjoyment budget. A 3-year ARM drastically reduces your initial interest rate, shaving a massive percentage off your baseline payments during the first 36 months. More often than not, buyers fail to calculate how much cumulative cash stays in their bank accounts during those crucial early years of ownership. It is simply economics: lowering your fixed overhead allows you to redeploy that capital into property upgrades, furnishings, or portfolio diversification. I would not be surprised to see buyers save a small fortune on interest alone, money that is far better kept in your pocket than handed to an institutional lender over a product you plan to refinance or sell shortly.
Why Are Over 50% of Transactions on the Big Island Cash and How Can an ARM Help Me Compete?
The Kona-Kohala Coast real estate market is flooded with liquidity, and by the end of the year, I anticipate that over 50% of all transactions will close in all-cash. If you require financing to secure your dream estate, competing against cash buyers feels like an uphill battle. Sellers love cash because it offers speed and certainty, leaving financed buyers out in the cold. However, implementing a strategic 3-year ARM positions you with strong purchasing power by lowering your monthly cost footprint and signaling to sellers that you are financially agile. More often than not, structured financing paired with strong earnest money bridges the gap against pure cash offers. It is simply economics: utilizing an ARM optimizes your debt-to-income profile during underwriting, making your offer cleaner and more attractive. I would not be surprised to see creative financing become the ultimate weapon for buyers who want to land luxury properties without liquidating their entire investment portfolio.
Should I Buy a Kohala Coast Vacation Rental with an ARM Instead of Waiting for Fixed Rates to Drop?
Waiting on the sidelines for fixed-rate mortgages to drop is a losing strategy when desirable Kohala Coast vacation rentals are actively appreciating. While you wait for market conditions to shift, home values climb and you miss out on peak rental income seasons. Utilizing a 3-year ARM allows you to secure the asset today, capturing immediate rental revenue from your condo or estate while capitalizing on a lower initial borrowing rate. More often than not, the income generated from a well-managed luxury vacation rental easily offsets the short-term nature of an ARM. It is simply economics: time in the market beats timing the market, especially in high-demand micro-climates like the Big Island. I would not be surprised to see proactive buyers build substantial equity today rather than gambling on macroeconomic forecasts. An ARM is your bridge to ownership, letting you collect high-end rental yields right now instead of sitting on the sidelines waiting for elusive rate cuts.
How Do I Safely Exit or Refinance an ARM Before the Fixed Period Ends at Mauna Lani Resort?
Executing a safe exit strategy from a 3-year ARM requires proactive planning long before the initial fixed-rate period expires at a premier destination like Mauna Lani Resort. Savvy luxury buyers never enter an adjustable-rate mortgage without a clear timeline to either sell the property, pay down a substantial portion of the principal, or refinance into a fixed-rate loan. More often than not, market interest rates fluctuate within a three-year window, opening up strategic refinancing opportunities when macroeconomic conditions improve. It is simply economics: keeping a close eye on federal monetary policy allows you to transition your loan smoothly before any rate adjustments kick in. I would not be surprised to see today’s ARM borrowers successfully refinance into lower fixed rates well before their 36-month clock runs out. By treating your mortgage as a dynamic financial instrument rather than a permanent anchor, you enjoy low initial payments while managing potential long-term exposure.
The Bottom Line: Stop Overpaying for Financing on Your Kona-Kohala Coast Dream Home
Navigating the luxury market along the Kona-Kohala Coast means looking past conventional mortgage myths and adopting strategies that preserve your wealth. By leveraging a 3-year ARM instead of overpaying for a rigid fixed-rate loan, you can potentially keep thousands of dollars in your pocket while competing against an avalanche of cash buyers.
“Stop letting fear of the unknown cost you a boatload of cash—smart, tactical financing is how you win in today’s Big Island luxury market.”
Frequently Asked Questions
Q: What is a 3-year ARM and how does it work for luxury real estate on the Big Island? A: A 3-year adjustable-rate mortgage offers a fixed interest rate for the first 36 months before it begins adjusting based on market indexes according to the loan terms. For Big Island luxury buyers, it can act as a short-term financial tool to secure high-end properties while reducing initial monthly mortgage payments compared to a higher-rate fixed loan.
Q: How do adjustable-rate mortgages compare to cash offers in competitive Kona-Kohala resort markets? A: While cash is king with over 50% of Big Island transactions closing without a loan, a well-structured ARM gives financed buyers a competitive edge by lowering monthly debt overhead. It allows you to present a strong, agile financial profile to sellers without having to liquidate your entire investment portfolio.
Q: What risks should I watch out for when choosing an ARM for a Hawaii vacation rental property? A: The primary risk is the rate adjustment that occurs after the initial 3-year fixed period ends, which could increase your monthly payments if rates remain elevated. Luxury buyers can manage this risk by planning for potentially higher payments, building equity, and evaluating refinancing or selling options before the adjustment period.
Q: When is the best time to refinance an adjustable-rate mortgage into a fixed-rate loan? A: The ideal time to refinance depends on market interest rates, closing costs, property equity, and your financial circumstances. Buyers should monitor market shifts and evaluate refinancing opportunities before the initial fixed-rate period expires.